 Admin
 October 7, 2026
 (0) Comment


Admin
October 7, 2026
(0) Comment
Bangladesh's capital market stands at a genuine inflection point. For the first time in a long while, the Government has given sustained, high-level attention to capital market reform, reflecting a recognition that a transparent, efficient, and vibrant market is not a peripheral concern but a precondition for the country's broader economic development. This alignment of political will with institutional reform creates a window of opportunity that market participants, regulators, and investors alike cannot afford to miss.
Reform agendas in capital markets succeed or fail on the strength of the confidence they command. Rules can be rewritten, and institutions restructured, but unless issuers, investors and intermediaries believe the system will function fairly and predictably, capital will not follow. Rebuilding that confidence - after decades of episodic volatility and eroded trust - therefore remains the core objective of the reform. Every initiative described below must ultimately be judged by whether it moves the needle on market confidence.
Bangladesh's capital market has long remained underdeveloped relative to the scale of the economy it serves. Years of irregularities, weak enforcement, and regulatory forbearance allowed structural weaknesses to persist instead of being corrected. The consequence has been a market that never developed the depth, liquidity or institutional credibility needed to serve as a genuine engine of capital formation. Businesses, meanwhile, have depended overwhelmingly on the banking system for long-term financing - a mismatch between short-term deposit-funded balance sheets and long-term capital needs that has strained banks without ever allowing the capital market to mature into its natural role.Neither side of the financial system has been well served by this imbalance.
Three structural issues stand out. First, an overly complex and, in places, outdated regulatory framework has discouraged quality issuers from coming to market. Second, the institutional capacity of core market infrastructure the stock exchanges, the depository, the central counterparty - as well as that of the intermediaries has not kept pace with what a modern market requires. Third, technology infrastructure across the ecosystem remains fragmented, undermining the efficiency and transparency of the market.
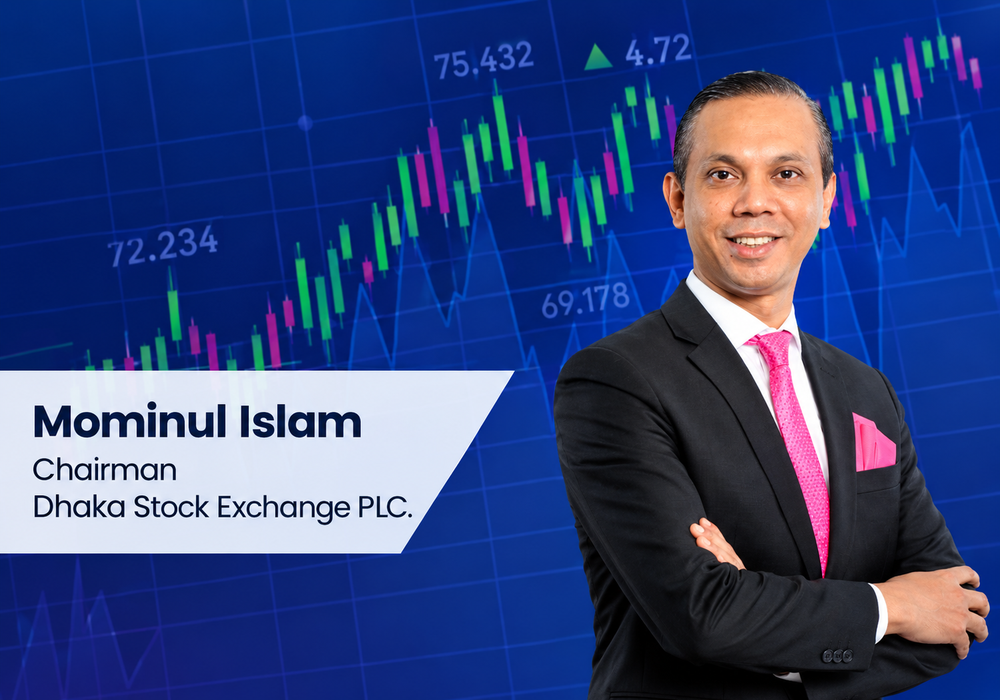
Encouragingly, a coordinated response is now underway. The national budget has, for the first time, explicitly outlined capital market reform as a policy priority, and at the highest level in the Government, capital market reform agenda has been reinforced - a clear signal that previous reform cycles lacked. A new regulatory Commission with a track record of credible leadership has been constituted to carry this agenda forward. On the regulatory front, key rules governing IPOs, direct listing and margin lending are under review, with the explicit aim of aligning Bangladesh's capital market with international best practice through deregulation and a more market-based approach. Product diversification is also advancing, with work underway on bonds, sukuk, a commodity exchange, REITs and ETFs; bond listing fees have already been cut significantly to encourage issuance. Market efficiency measures - including T+1 settlement and script netting - are progressing through implementation phase. Institutional strengthening is equally central. At the Dhaka Stock Exchange, work is underway on governance structure, an effective organogram, and performance management systems to build human resource capacity for the long term. Steps have also been taken to operationalize the Central Counterparty (CCBL), a long-pending piece of market infrastructure. On technology, a mid-term integrated infrastructure programme is being developed, alongside upgrades to DSE's matching engine and surveillance systems, a fully digitized IPO process at the BSEC, and an XBRL-based reporting solution on the horizon that should eliminate the hard-copy filing burden long faced by listed companies and intermediaries. A centralized and integrated Order Management and Back-office Management Solution for the TREC Holders has also been envisioned, which can significantly boost market efficiency and radically change the monitoring and surveillance ecosystem.
The Government's role extends beyond policy pronouncements. Fiscal incentives for capital market participation have been put in place, preparations for the country's first-ever sovereign bond issuance are underway, and there is clear intent to use the capital market as a vehicle for financing long-term public infrastructure projects - a shift that would deepen the market while easing pressure on the ailing banking sector.
Taken together, these initiatives point toward a comprehensive roadmap for Bangladesh's graduation from Frontier to Emerging Market status within the next five years. That reclassification would be more than symbolic: it would place Bangladesh squarely on the radar of a much broader universe of institutional capital, both local and international, that is currently structurally excluded or underweight. For foreign investors, the opportunity lies precisely in this transition period. Markets rarely offer the combination seen in Bangladesh today - strong political commitment, an active regulatory reform pipeline, and valuations that have not yet priced in the structural improvements underway. Confidence, once rebuilt, tends to compound. Investors who engage early in this reform cycle are best positioned to benefit as Bangladesh's capital market moves toward the scale, depth and credibility its economy has long deserved.